An education loan for study abroad is how most Indian students actually fund their international education — very few families pay the full cost upfront in cash. But the loan landscape has real complexity: secured vs unsecured options, wildly different interest rates between public and private lenders, and collateral requirements that catch a lot of first-time applicants off guard. Here’s what to actually know before you apply.
Understanding Your Education Loan for Study Abroad Options
1. Public Sector Banks vs Private Banks vs NBFCs
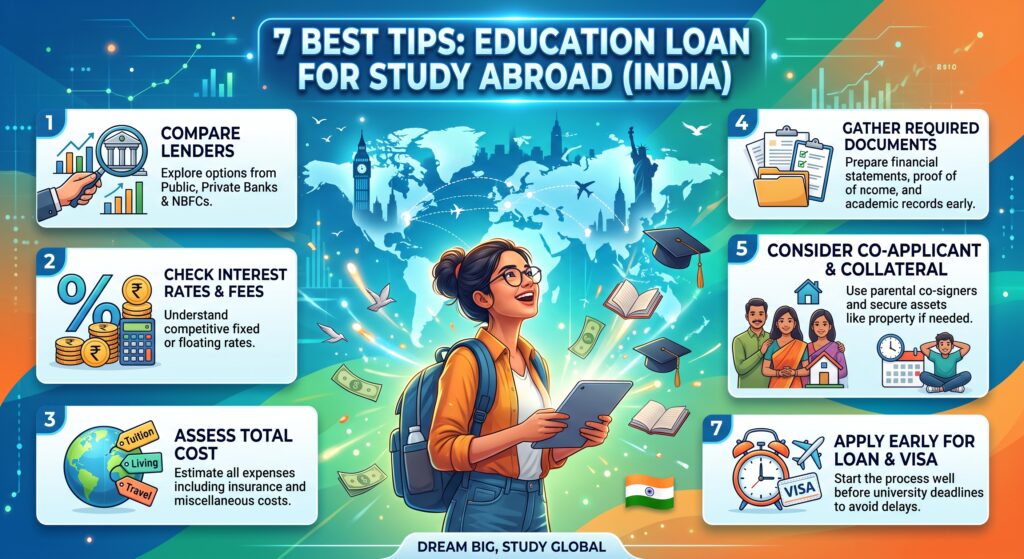
Public sector banks (SBI, Bank of Baroda, PNB, and similar) generally offer lower interest rates but tend to have slower processing and stricter collateral requirements. Private banks and NBFCs (like HDFC Credila, Avanse) often process faster and are more flexible on collateral, but typically charge higher interest rates in exchange. The right choice depends on your timeline and whether you have collateral available.
2. Secured vs Unsecured Loans
Loans above a certain amount (commonly around ₹7.5-10 lakhs, though this varies by lender) usually require collateral — property, fixed deposits, or other secured assets. Below that threshold, some lenders offer unsecured loans based primarily on academic profile and co-applicant income, though these typically carry higher interest rates than secured options.
3. The Co-Applicant Requirement
Virtually every education loan needs a co-applicant — usually a parent or guardian with a stable, demonstrable income. The co-applicant’s income and credit history matter significantly to the loan approval and the interest rate you’re offered, so this is worth sorting out early rather than assuming it’s a formality.
4. Moratorium Period — Understand Before You Sign
Most education loans offer a moratorium period (course duration plus a grace period, often 6-12 months after course completion) during which you’re not required to make full EMI payments. Some loans require interest-only payments during this period, while others fully defer — this materially affects your total interest cost, so it’s worth understanding exactly which type you’re being offered.
5. Interest Rate Type — Fixed vs Floating
Education loans can carry fixed or floating interest rates. Floating rates fluctuate with market conditions (potentially rising or falling over your loan term), while fixed rates lock in a rate for predictability. Given loan tenures often run 10-15 years, even small rate differences compound significantly over the life of the loan — worth comparing carefully rather than defaulting to whichever option a bank presents first. education loan for study abroad
6. Tax Benefits Under Section 80E
Interest paid on an education loan for higher studies (including abroad) is eligible for a tax deduction under Section 80E of the Income Tax Act, with no upper limit on the deduction amount, available for up to 8 years or until the interest is fully repaid, whichever is earlier. This is worth factoring into your actual cost-of-borrowing calculation, not just the headline interest rate — though the specific eligibility and current provisions are worth confirming with a CA given tax rules can change. education loan for study abroad
7. Apply Early — Loan Processing Takes Time
Loan sanction, especially for secured loans requiring property valuation and legal verification, can take several weeks. Starting the loan process only after your visa is close to filing creates unnecessary time pressure — begin loan applications as soon as you have an admission offer, running the process in parallel with visa documentation rather than sequentially after it. education loan for study abroad
What Lenders Actually Look At
- Academic profile and the reputation/ranking of the admitting institution
- Co-applicant’s income stability and existing credit obligations
- Collateral value and clear legal title (for secured loans)
- The specific country and course — some lenders have different risk appetites for different destinations
- Your own academic and, if applicable, work history
Common Mistakes to Avoid
- Applying to only one bank instead of comparing at least two or three offers on rate, processing time, and moratorium terms
- Not understanding whether interest accrues (and compounds) during the moratorium period before signing
- Underestimating the collateral valuation and legal documentation timeline
- Forgetting to factor Section 80E tax benefit into your real cost-of-borrowing comparison
Frequently Asked Questions
How much can I typically borrow with an education loan for study abroad?
This varies significantly by lender, collateral availability, and the cost of your specific program — public sector banks and private lenders both offer a range of loan amounts, so it’s worth getting a specific quote based on your actual admission offer rather than assuming a generic figure. education loan for study abroad
Do I need collateral for every education loan?
Not necessarily — smaller loan amounts are sometimes available unsecured based on academic profile and co-applicant income, though secured loans generally offer better rates once collateral is involved. education loan for study abroad
When should I start the education loan process?
As soon as you have an admission offer (or even a strong conditional offer) — running it in parallel with your visa documentation, rather than waiting until after, saves significant time pressure later. education loan for study abroad
How Goyad Travel Helps
We don’t disburse loans ourselves, but we help you understand how your loan timeline fits into your overall study abroad plan — sequencing it alongside your visa filing, blocked account or financial proof requirements, and forex needs so nothing becomes a last-minute scramble. This fits within our broader study abroad consultancy and pairs well with our cost comparison guide for budgeting your total need upfront. education loan for study abroad
Planning your study abroad finances? Talk to us on WhatsApp or call +91 7997226661 / +91 7997226662.
📍 Goyad Travel — Road No. 11, Reliance Humsafar Building, Banjara Hills, Hyderabad, Telangana | View on Google Maps
📧 contact@goyadtravel.com | 🕐 Monday–Saturday, 9:00 AM – 7:00 PM